Have you checked auto loan interest rates or car insurance bills recently? If you have, you know how painful those numbers look right now. Between elevated vehicle prices and higher borrowing costs, locking yourself into a five-year loan or a rigid 36-month lease feels like a serious gamble. What happens if you start working remotely full-time, decide to relocate to a new city, or want to switch to an electric vehicle next year?
This uncertainty is driving a major shift in how people access wheels. The global car subscription market is already valued at over $5 billion, and industry projections expect it to climb past $16 billion over the next decade.¹
Instead of treating a vehicle as an expensive personal asset that you purchase, finance, and maintain, drivers are treating cars like software. You pay for access when you need it, and you pause or cancel your plan when your life changes.
The Evolution of Ownership and Why We Are Moving Away from Traditional Leasing
For decades, the path to getting a car was predictable. You saved up a down payment, spent an exhausting Saturday at a dealership showroom, and signed papers committing yourself to 48 to 72 months of debt.
Even standard leasing, long marketed as the flexible alternative, comes with rigid rules. Most leases lock you in for three full years. If you want out early because your lifestyle has changed, you face crushing early-termination fees.
Cultural habits around ownership have changed dramatically. We stream music, rent software, and lease smartphones through yearly upgrade programs. Long commitments simply feel outdated.
Vehicle subscriptions disrupt that old model by decoupling personal mobility from long-term financial debt. You get private access to a reliable vehicle without taking on thousands of dollars in negative equity or signing your name to a multi-year loan.
Decoding the Model and How Monthly Vehicle Memberships Function
People often call this setup "Netflix for cars," and the comparison is pretty accurate.
With a standard lease or purchase, your car payment is only the beginning. You still have to purchase an auto insurance policy, pay for registration and state inspections, replace worn tires, and handle routine maintenance out of pocket.
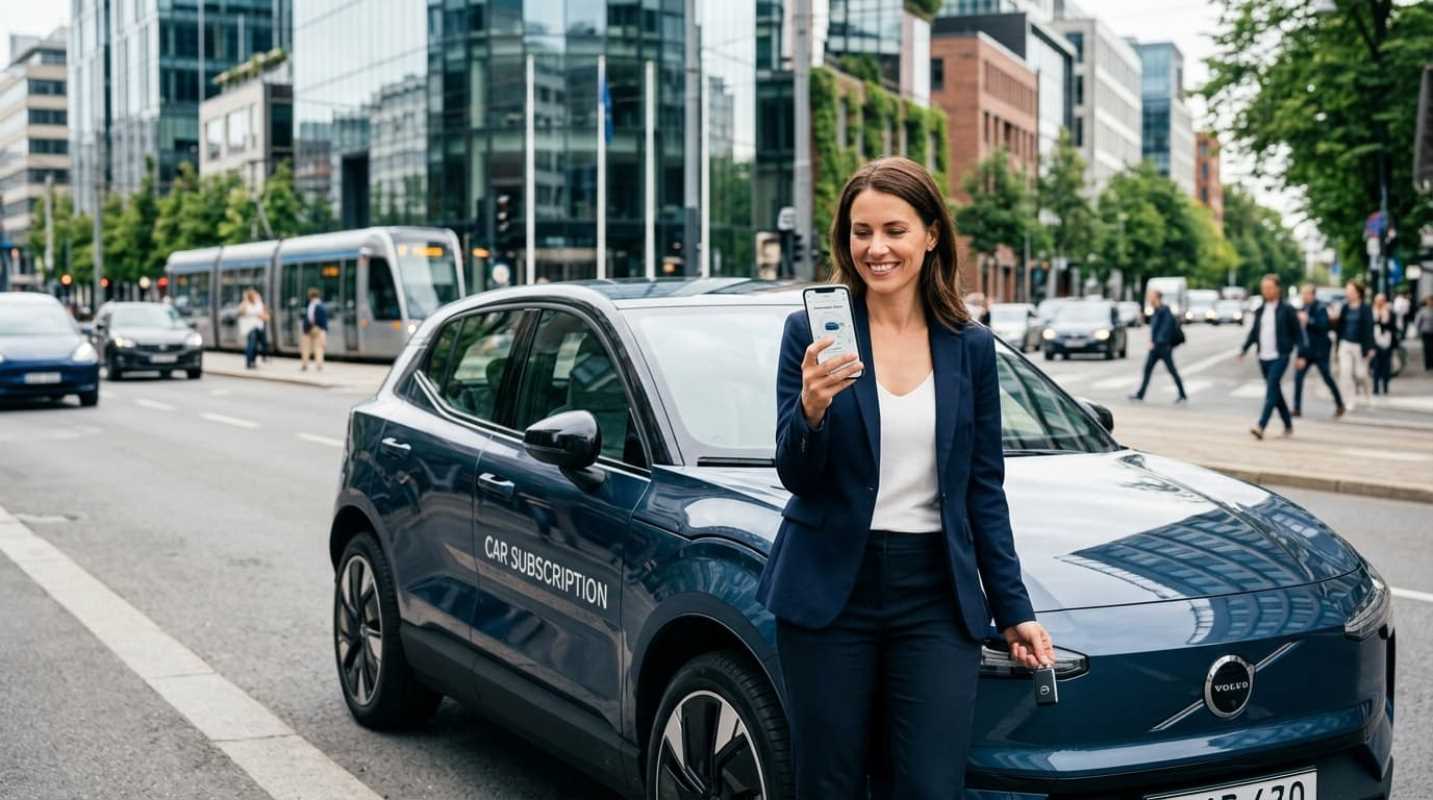
Car subscriptions take all those headache-inducing expenses and combine them into a single, predictable monthly charge. You handle everything directly through an app or website. You choose your car, complete a digital identity check, select your term, and arrange delivery or pickup.
Everything you need to stay street-legal is bundled into one monthly rate
• Complete insurance: Liability, collision, and complete coverage are built directly into your monthly membership fee, eliminating the hassle of separate insurance shopping.
• Routine maintenance and repairs: Oil changes, scheduled service checkups, brake pad replacements, and normal wear and tear are covered by the subscription company.
• Roadside assistance: If you get a flat tire, run out of charge, or lock your keys inside, 24/7 emergency dispatch is included.
• Registration and taxes: The provider owns and registers the vehicle, saving you annual trips to the DMV and unexpected registration bills.
Terms typically run anywhere from 28 days to 12 months. When your term wraps up, you can renew, return the keys, or swap into a completely different model.
If you want to explore the leading platforms currently offering turnkey vehicle memberships, here are our top picks.
Weighing the Pros and Cons of Going Subscription
Before you download an app and order a crossover to your driveway, you need a realistic look at the numbers. Subscriptions offer incredible convenience, but they come with trade-offs.
A major friction point is price expectation. Deloitte's Global Automotive Consumer Study revealed that around 80% of surveyed consumers expect an all-inclusive car subscription to cost under $500 per month.² In reality, most turnkey services start around $650 and can exceed $1,200 for premium models.
Even with that pricing gap, younger demographics are flocking to memberships. Between 28% and 35% of Gen Z and Millennial drivers say they prefer vehicle subscriptions over outright ownership.³
Here is how the main benefits and drawbacks stack up
• Financial predictability: You know your exact transportation cost down to the dollar each month, protecting your budget from sudden repair shocks.
• No long-term debt: You avoid signing a multi-year loan agreement that stays tied to your personal credit profile for years.
• Zero down payment: Unlike traditional car purchases that demand thousands down to get a reasonable rate, subscriptions usually only require your first monthly fee and a modest security deposit.
• Higher ongoing cost: Subscribing to a car for three consecutive years is noticeably more expensive than buying or financing that same model.
• Strict mileage restrictions: Most providers limit you to 800 to 1,200 miles per month, and excess mileage penalties can add up quickly.
• Zero asset value: You build no financial equity in the car. When your contract ends, you hand the keys back with nothing to show on your balance sheet.
Who actually wins with this arrangement? Subscriptions are ideal for digital nomads, contract workers on temporary assignments, and drivers who want to test an electric car for six months without worrying about battery depreciation. On the other hand, if you are a rural commuter putting 25,000 miles a year on your vehicle, a standard purchase is still the more sensible economic path.
Is a Subscription Right for Your Lifestyle in 2026?
Deciding whether a vehicle subscription makes financial sense comes down to calculating your true total cost of ownership.
Too many drivers compare a $750 subscription fee to a $450 lease payment and assume the subscription is a terrible deal. But take a closer look at the math.
Once you add a $180 monthly insurance premium, $60 for maintenance reserves, registration fees, and the opportunity cost of a $4,000 cash down payment, that $450 lease is actually costing you over $750 each month. In high-cost urban regions, a bundled membership often matches or beats the true monthly cost of leasing.
What you are purchasing with a subscription is agility. You trade long-term financial equity for total flexibility, simple digital management, and peace of mind.
If you plan to buy a dependable sedan and drive it until the wheels fall off in 2035, stick with a traditional purchase. But if you value your time, move frequently, or want to drive newer vehicles without the bureaucratic headaches of ownership, subscribing might be the best garage upgrade you can make.
Sources:
1. Mordor Intelligence - Car Subscription Market Report
https://www.mordorintelligence.com/industry-reports/car-subscription-market
2. Deloitte - Global Automotive Consumer Study
https://www.deloitte.com/uk/en/about/press-room/deloittes-global-automotive-consumer-study.html
3. Motor Finance Online - Younger Drivers Lean Towards Car Subscription Services
https://www.motorfinanceonline.com/news/younger-drivers-lean-towards-car-subscription-services-over-ownership-deloitte/
*This article on Everyknown is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*